An Often-Overlooked Need
Offer additional valuable benefits to help reward and retain your company leaders. Executive disability insurance is an important add-on to any strong benefits program.
When it comes to disability insurance, in all likelihood, your executives are severely under-covered. MBS is here to help you close this gap and round out your executive benefits offerings.
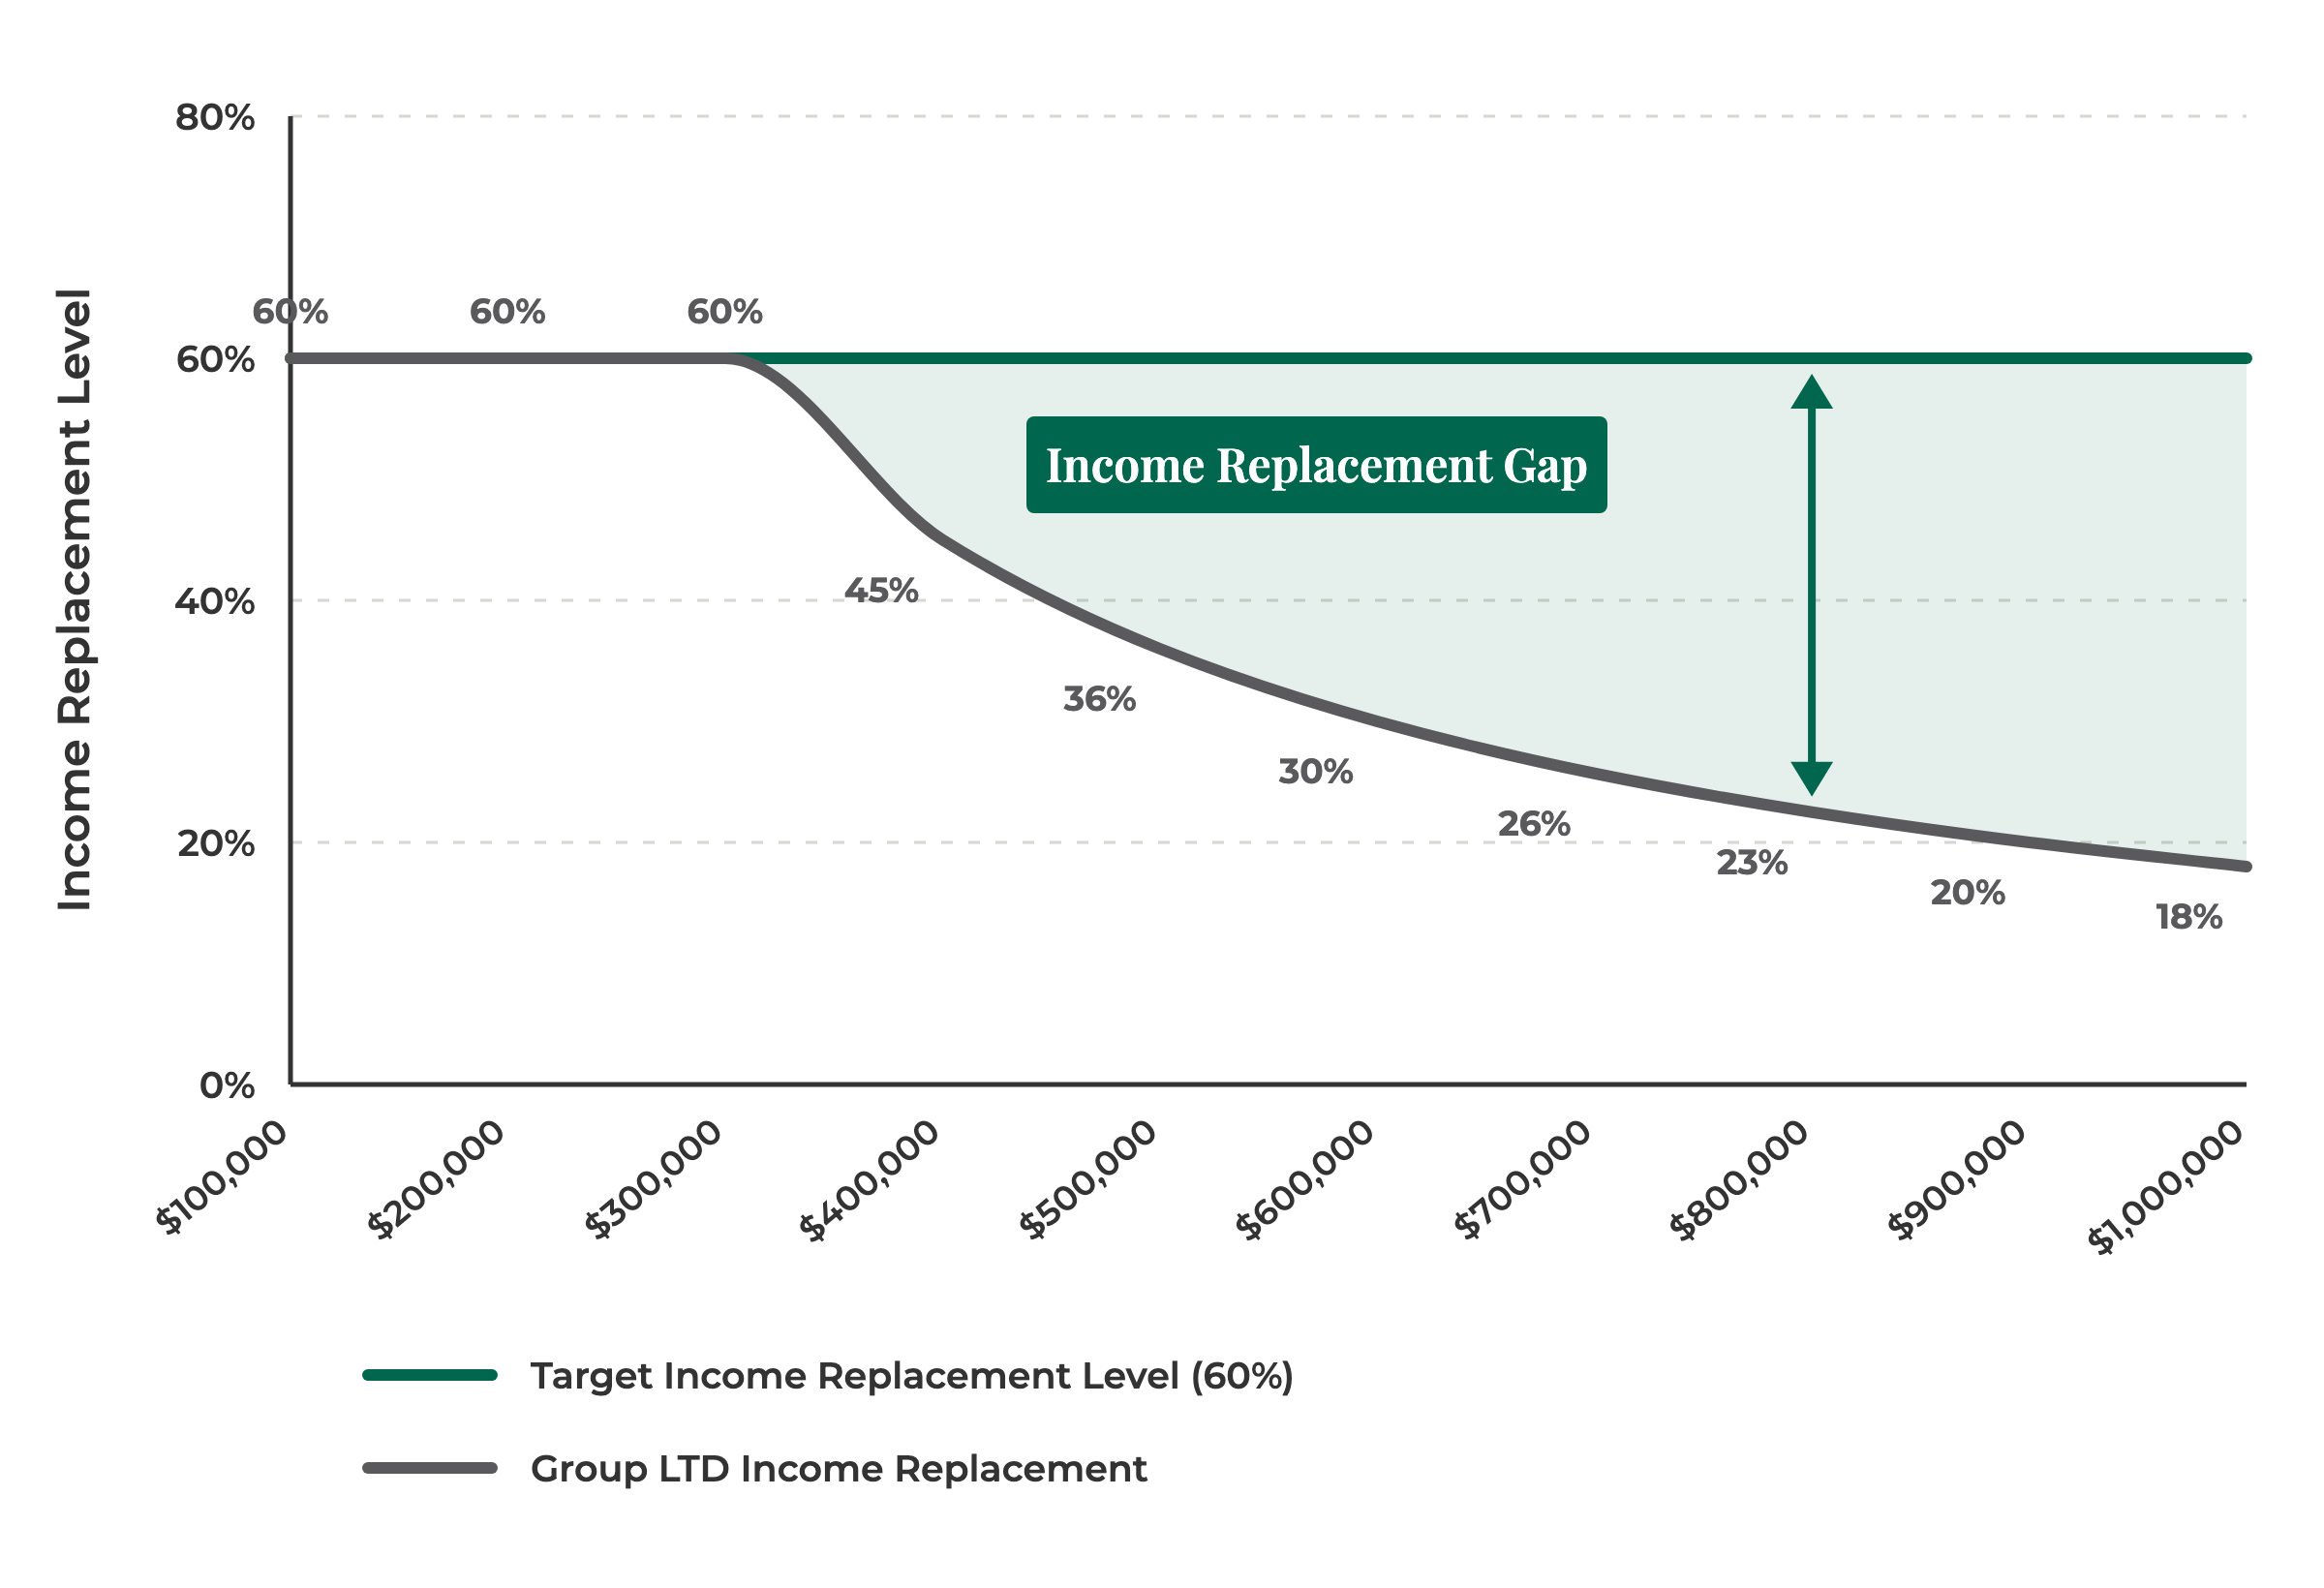
While most companies offer long-term disability for all employees, 95% of the time, it covers only salary and not variable compensation. Benefits when paid are also taxable, and as a result, your key employees probably do not have the income protection they expect. With nearly one in four people likely to need disability coverage before retirement age1, supplemental executive disability is an important added benefit.
1 Social Security Administration, https://www.ssa.gov/oact/NOTES/ran6/an2025-6.pdf Table A, Column 1 (Probability of Disability Before NRA)
An Executive Benefits Resource You Can Count On
Working with MBS to provide your executives with the added financial clarity of executive disability insurance is smart business. In addition to providing a valuable benefit these essential team members will appreciate, you can work with an independent resource you know and trust.
Strong Relationships
And Experience
We work with leading providers and have helped clients ensure executive disability is more than just a preventive measure. We identify insurance companies for the top layer of coverage and can bring in additional international providers for the most senior, highly paid clients who need additional coverage.
Access To
Proprietary Products
Our relationship with M Financial offers access to exclusive executive disability products through Unum.
Independent
And Unbiased
Count on an objective partner who will do a full market study to ensure you get competitive pricing and the right provider for your needs.
Executive
Education
We work directly with your executives to ensure they understand the value of their executive disability benefits.
Executive Disability
Expertise By The Numbers
13
Clients
18
Years Average Client Relationship
2,064
Policies
Delivering On An Essential Need
The financial consequences of a disability are extreme. Executives and senior managers often derive a greater proportion of their annual income from variable compensation which is generally excluded in group disability programs. High-income earners are also more likely to be the sole wage owner in a household. And in the event of a disability, employer medical and dental insurance, retirement savings, and company matching contributions typically stop. Also surprising to recipients of disability benefits, they are usually fully taxable.
Qualifying for disability insurance independently can prove challenging. Given that individuals are 4X more likely to experience disability than death during their working years, this is essential coverage for your key employees.
Implementing An Executive Disability Insurance Program
Helping your executives protect more of their income in the event of a disabling injury or illness is an important financial wellness benefit you can offer them.
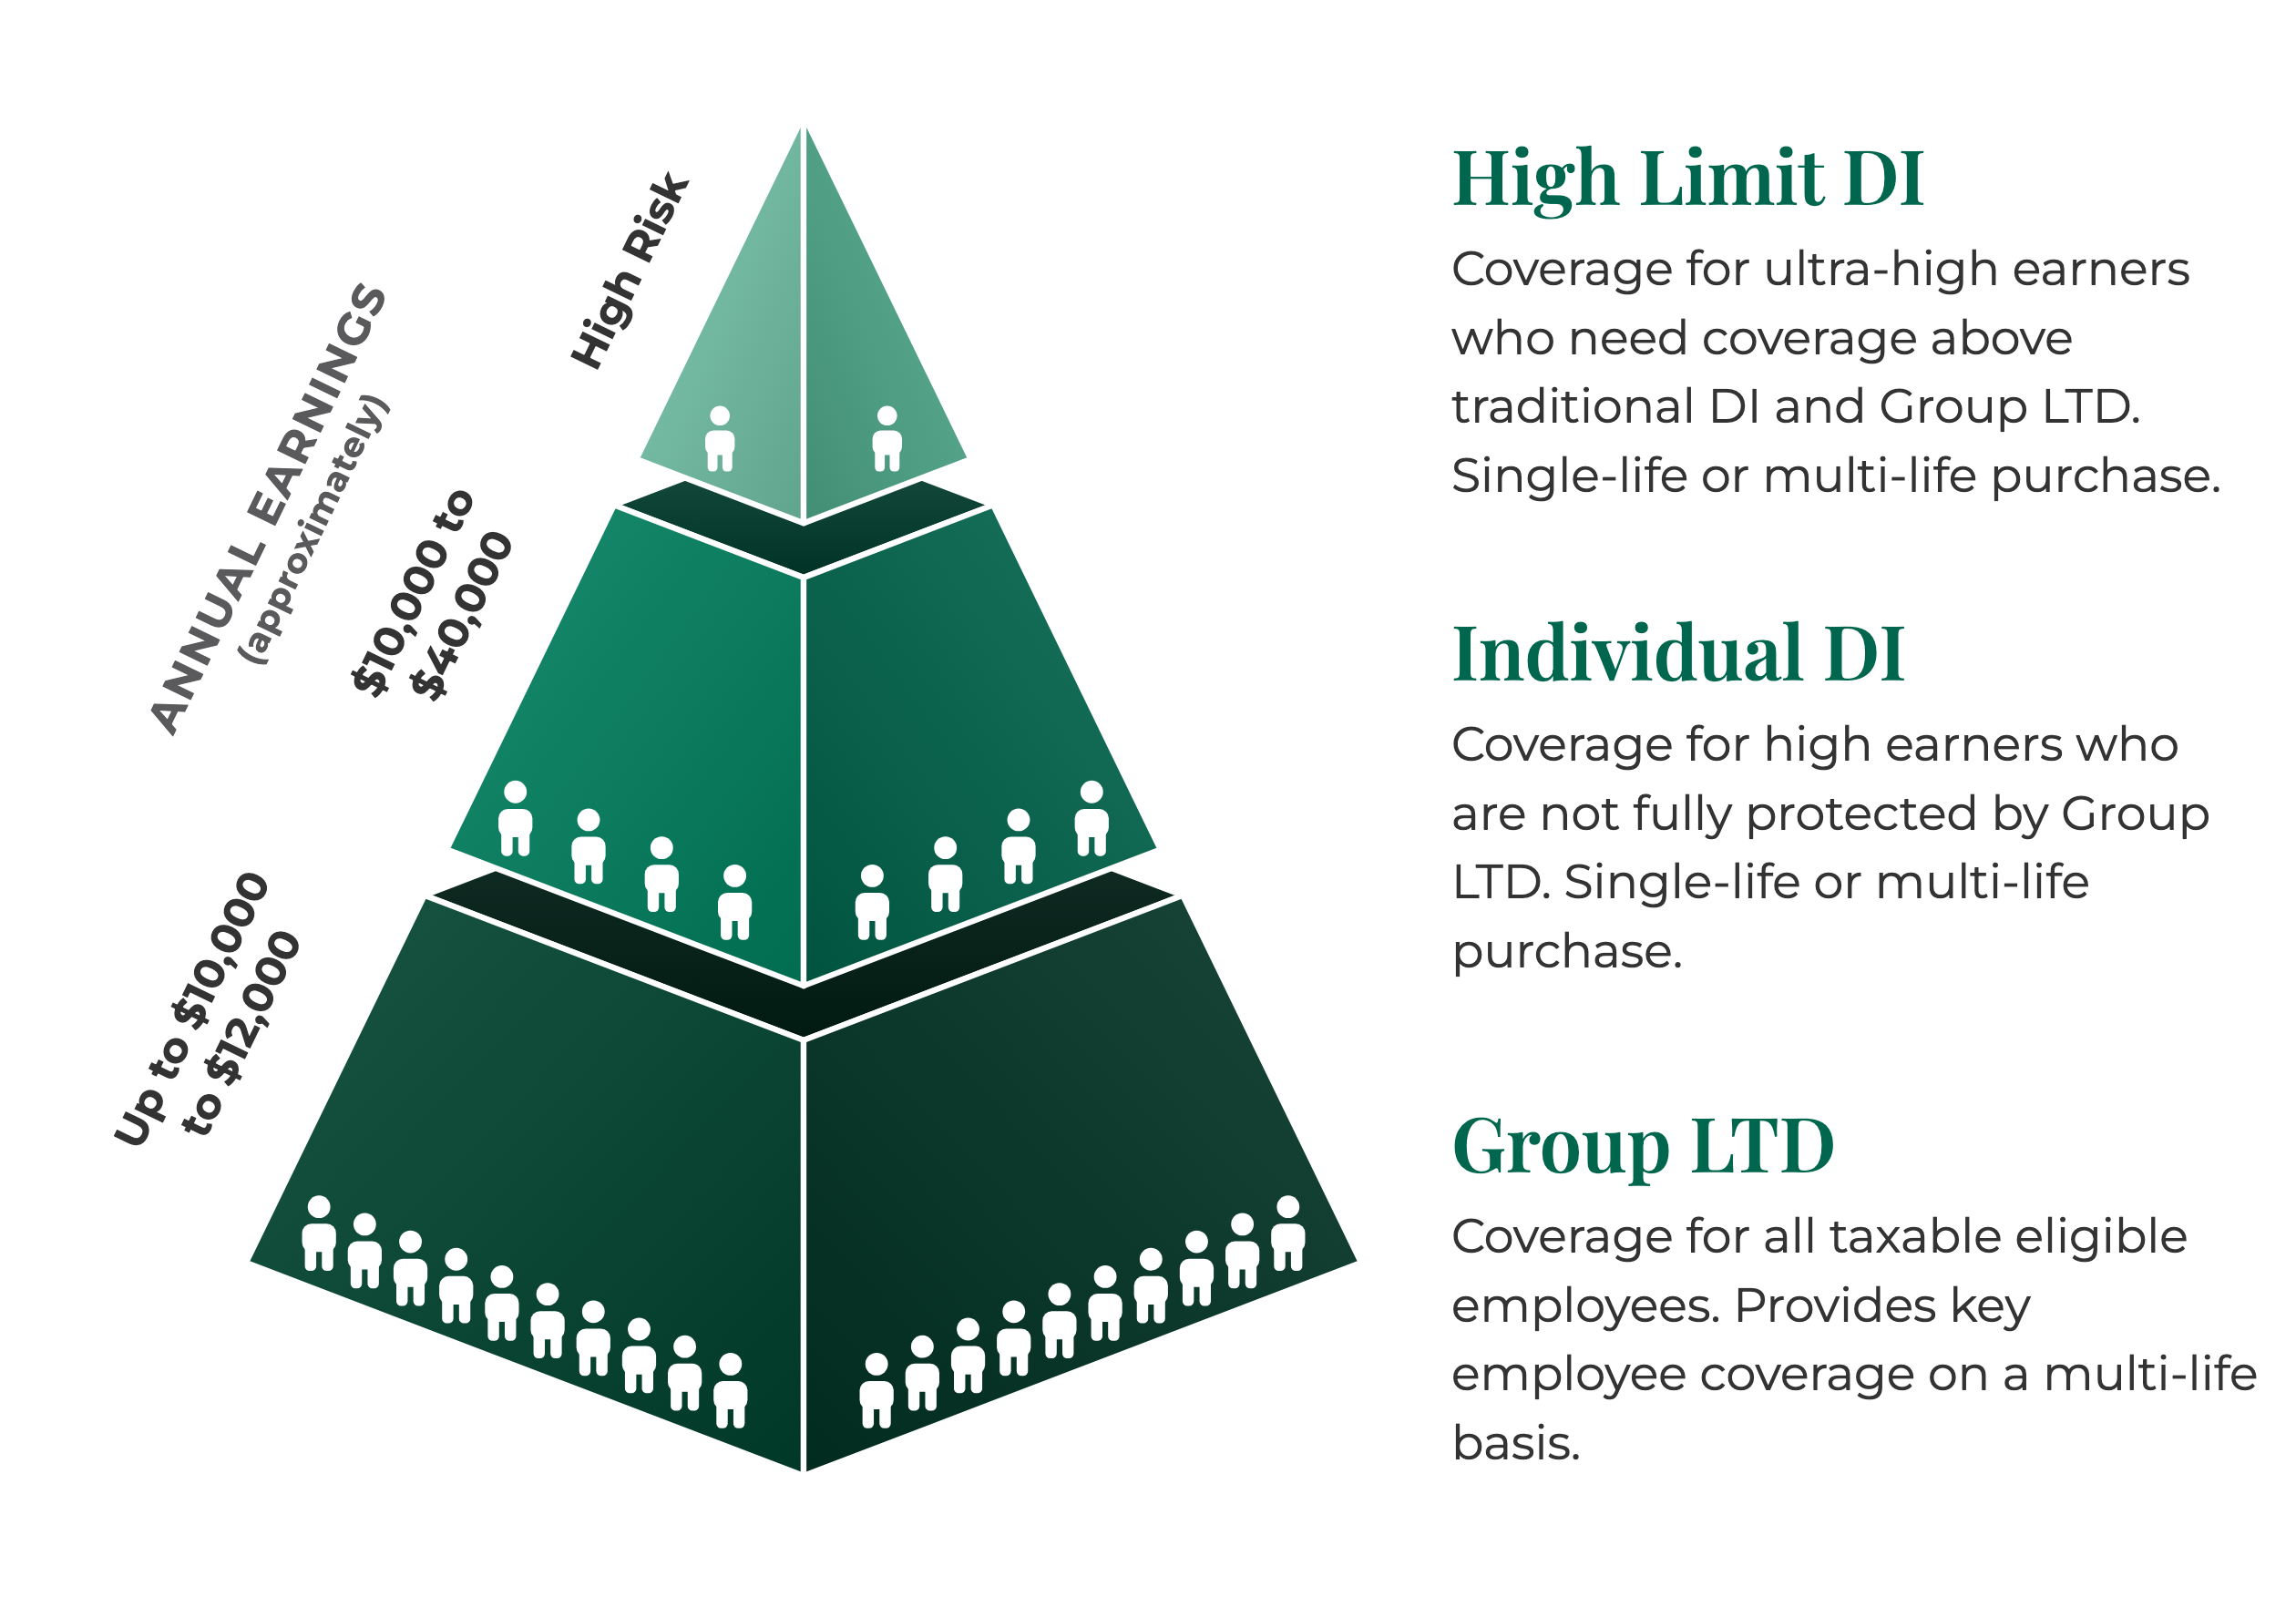
- Individual executive disability insurance is supplementary to your existing group long-term disability (LTD).
- The two coverages work together to provide a more complete income protection solution.
- Long-term disability typically covers a percentage of your employee’s base salary after 180 days of disability and is typically taxable to the employee.
- Supplementary executive disability insurance can cover up to 80% of total compensation (salary and incentive) and can be combined with group coverage.
- Supplemental insurance benefits cover incentive pay that is not typically covered by group plans and is not typically taxable to the employee.
- Participants who elect the full amount of coverage they qualify for are eligible for periodic coverage increases to match compensation increases.
- The policy is portable, meaning employees can take it with them if they terminate employment and keep the discounted rates as long as premiums are paid.
- Features and pricing are locked in until age 65, unlike group LTD that may be changed by the insurance company at any time.